YouTube · Operations & Supply Chain Management UniversityOriginal video
READ & KEEP
The explanation, unpacked.
Reviewed learning material · Video analysis · EnglishRead the full overview
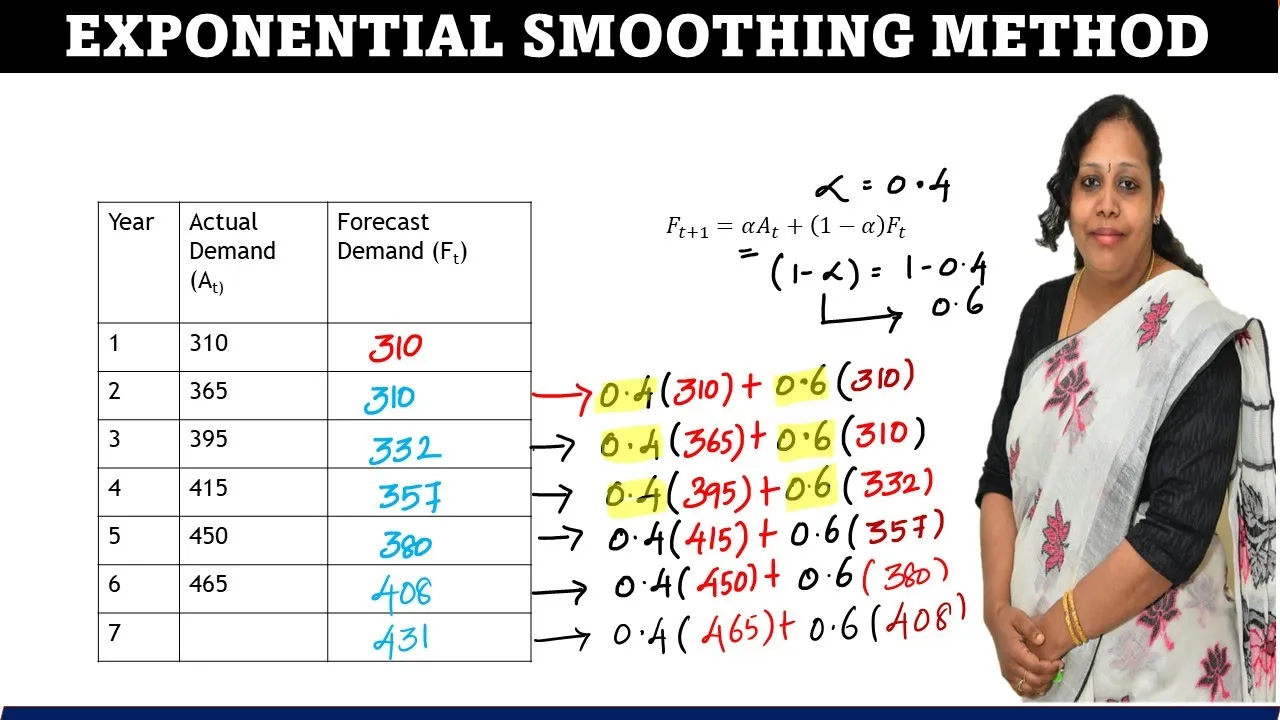
This introductory lecture segment defines exponential smoothing as a quantitative time series forecasting method. The speaker explains that it is a weighted moving average technique where data points are weighted by an exponential function to smooth out irregular fluctuations. The core formula, Ft=Ft−1+α(At−1−Ft−1), is presented, and each variable is defined: Ft is the new forecast, Ft−1 is the previous forecast, At−1 is the previous actual demand, and α is the smoothing constant constrained between 0 and 1. The term (At−1−Ft−1) is identified as the error term. The slide also notes that if a starting forecast is not given, one should assume F1=A1. Finally, the instructor clarifies that students do not need to learn exponential smoothing with trend adjustment for this specific lesson.
This 108-second lecture segment introduces simple exponential smoothing through the update formula Ft=Ft−1+α(At−1−Ft−1) and then focuses on the meaning of the smoothing constant α. The slide and narration explain that α lies between 0 and 1, that α=0 leaves the forecast unchanged at Ft−1 and therefore ignores recent data, and that α=1 turns the method into the naive forecast Ft=At−1. The speaker then connects these endpoint cases to practice: use a smaller α when demand is stable and you want stronger smoothing, and use a larger α when demand is volatile and you want faster response. The segment closes by stressing that the real objective is forecast accuracy, so α should be tuned by trial and error against historical data to achieve the lowest forecast error rather than chosen by intuition alone.
This 108-second lecture segment explains exponential smoothing through the role of the smoothing constant α. It first presents the update formula Ft=Ft−1+α(At−1−Ft−1) and the endpoint cases α=0 and α=1. A graph then compares actual demand with smoothed forecasts for α=0.1 and α=0.5 to show the trade-off between smoothing and responsiveness. The clip closes with a car-dealer word problem using α=0.20 to forecast March demand from February values.
This video explains the exponential smoothing method for forecasting demand. It introduces the formula Ft=Ft−1+α(At−1−Ft−1) and discusses the role of the smoothing constant α. The speaker then applies the formula to a practical example, calculating the forecasted demand for March based on predicted and actual demand for February.
This short clip displays a slide explaining an exponential smoothing example for forecasting car demand. It provides the formula Ft=Ft−1+α(At−1−Ft−1) and walks through a calculation where a previous forecast of 142 and actual demand of 153 are used with α=0.20 to predict a new demand of approximately 144 cars.
Use the learning inspector for key ideas and moments, or open the reading tabs for the complete notes.
Generated from the video's visuals and explanation; not verbatim speech.
Welcome to this introduction to exponential smoothing, a quantitative method used in time series forecasting. This technique is highly practical because it allows us to generate forecasts for future periods by applying a smoothing constant to past data.
Fundamentally, exponential smoothing is a weighted moving average forecasting technique. Unlike simple moving averages that assign equal weights to all past observations, exponential smoothing assigns weights to data points based on an exponential function. This means more recent data points receive higher weights, which effectively smooths out irregular fluctuations in the time series.
Let's look at the mathematical formula for exponential smoothing: Ft=Ft−1+α(At−1−Ft−1). In this equation, Ft represents the new forecast for the current period t. The term Ft−1 is the forecast made for the previous period, and At−1 is the actual demand observed in that previous period. The variable α, known as the smoothing constant, dictates the weight given to the most recent error. It is strictly bounded such that 0≤α≤1; it cannot be a negative number. The expression (At−1−Ft−1) is the error term, calculated as the actual demand minus the previous forecast. Additionally, if a starting forecast is not provided for a problem, standard practice is to assume that the initial forecast equals the initial actual demand, or F1=A1.
As a final note on the scope of this lesson, you are not required to learn exponential smoothing with trend adjustment, which can be found on page 120 of the textbook. Our focus remains strictly on the basic exponential smoothing model.
The clip opens on a slide defining exponential smoothing with the update rule Ft=Ft−1+α(At−1−Ft−1), where Ft is the new forecast, Ft−1 is the previous forecast, At−1 is the previous actual demand, and α is the smoothing constant restricted to 0.0≤α≤1.0.
The lecturer then shifts attention specifically to the effect of α, treating it as the key parameter that determines how strongly the forecast responds to the latest error term (At−1−Ft−1).
When α is close to zero, the correction added to the old forecast is very small. Algebraically, at the endpoint α=0, the formula collapses to Ft=Ft−1, so the forecast does not update from recent observations and behaves like strong smoothing toward an average.
Because of that, the speaker recommends a low α when the underlying demand or sales series is stable and the analyst wants the forecast to remain close to a longer-run average rather than chase short-term fluctuations.
At the opposite endpoint, when α is close to one, the forecast reacts almost fully to the previous error. If α=1, the update becomes Ft=Ft−1+1(At−1−Ft−1)=At−1, which is exactly the naive forecast that copies the most recent actual value.
The lecturer therefore advises using a higher α when demand is volatile or likely to change, because the model must respond quickly to the newest observation instead of smoothing heavily.
The discussion then broadens from endpoint behavior to model selection: the ultimate goal is not simply more smoothing or more responsiveness in the abstract, but the most accurate forecast possible regardless of technique.
To illustrate the risk of arbitrary choice, the speaker notes that someone may believe a selected α works well, yet without historical data we cannot tell whether that judgment reflects genuine predictive skill or merely one unusually favorable month.
For practitioners in operations and forecasting, the implied procedure is to test multiple values of α by trial and error, compare resulting forecast errors on historical data, and choose the smoothing constant that yields the lowest forecast error.
The segment ends by restating the central criterion: tuning α is justified insofar as it helps achieve the lowest forecast error and therefore the best practical forecast performance.
The segment opens on a slide titled "Effect of the Smoothing Constant." The central formula is Ft=Ft−1+α(At−1−Ft−1), where Ft is the new forecast, Ft−1 is the previous forecast, At−1 is the most recent actual observation, and α is restricted to 0.0≤α≤1.0.
The lecturer frames α as a tool for reducing forecasting error when only limited data are available, because the update uses just the previous period's actual value and forecast.
Two endpoint cases are shown explicitly. If α=0, then Ft=Ft−1+0 and therefore Ft=Ft−1; the slide states that the forecast does not reflect recent data.
If α=1, then Ft=Ft−1+1(At−1−Ft−1), which simplifies to Ft=At−1. In words, the next forecast becomes exactly the latest observed demand.
The slide then summarizes the trade-off: values nearer zero produce more smoothing and slower adjustment to forecast errors, while values nearer one produce greater responsiveness and less smoothing. The practical goal is the most accurate forecast, typically identified by the lowest forecast error.
The presentation switches to a graph titled "Impact of Different α." At first only a blue curve labeled "Actual demand" is visible on axes "Quarter" and "Demand." The lecturer describes the shape qualitatively as down, then up, then down again, with a slight overall upward tendency.
A purple curve labeled α=0.1 is added. Visually it is much flatter than the blue actual-demand curve. The narration interprets this as the model "taking this average" and smoothing the series out, so it misses sharp movements such as those around quarters 3 and 6.
A green curve labeled α=0.5 is then added between the blue and purple lines. This curve drops and rises more quickly than the α=0.1 line, illustrating the claim that a larger α is more responsive to changes in demand.
The three-line comparison makes the parameter meaning concrete: small α gives strong smoothing and lag, while larger α tracks recent fluctuations more closely.
The final slide, "Exponential Smoothing Example," presents a numerical problem. A car dealer forecast February demand at 142 Ford Mustangs, actual February demand was 153 cars, and management chose α=0.20.
Using the same formula Ft=Ft−1+α(At−1−Ft−1), the task is to forecast March demand. Substituting the displayed values gives Ft=142+0.20(153−142).
The lecturer notes that choosing α=0.2 means staying relatively close to the average rather than reacting sharply. The clip ends before the spoken arithmetic conclusion, although the displayed data imply Ft=144.2 cars.
The speaker begins by discussing the choice of the smoothing constant, α. They explain that a lower α, such as 0.2, is chosen when the goal is to keep the forecast smooth and close to the average, rather than reacting strongly to a single outlier month like February's high sales of 153 Mustangs.
Next, the speaker demonstrates how to use the exponential smoothing formula to calculate the forecast for March. They substitute the given values into the formula: Ft=Ft−1+α(At−1−Ft−1). With F_{Feb} = 142, A_{Feb} = 153, and α=0.20, the calculation proceeds step-by-step: 142+0.20(153−142)=142+0.20(11)=142+2.2=144.2.
Finally, the speaker rounds the result to the nearest whole number, concluding that the forecasted demand for March is approximately 144 cars. They summarize that exponential smoothing is a useful tool, especially when historical data is limited, and that the smoothing constant can be adjusted to achieve the desired level of responsiveness in the forecast.
The video presents a static slide titled 'Exponential Smoothing Example'. The problem describes a car dealer who predicted February demand for 142 Ford Mustangs, but the actual demand was 153 cars. With a smoothing constant α=0.20, the goal is to forecast March demand.
The core formula displayed is Ft=Ft−1+α(At−1−Ft−1). This means the new forecast equals the old forecast plus the smoothing constant times the error (actual minus forecast) from the previous period.
The calculation proceeds as follows:
1. Identify variables: Previous forecast F(Feb)=142, Previous actual A(Feb)=153, α=0.20.
2. Substitute into formula: March Fcst=142+0.2[153−142].
3. Calculate error: 153−142=11.
4. Apply smoothing: 0.2×11=2.2.
5. Final result: 142+2.2=144.2, which rounds to 144 cars.
Knowledge cards
01
Exponential Smoothing Definition
Exponential smoothing is a quantitative time series forecasting method. It is a type of weighted moving average where data points are weighted by an exponential function, giving more importance to recent observations. This process helps to smooth out irregular fluctuations in the data, making underlying trends easier to identify and forecast.
02
Exponential Smoothing Formula
The core formula for exponential smoothing is Ft=Ft−1+α(At−1−Ft−1). Here, Ft is the new forecast for period t, Ft−1 is the previous period's forecast, and At−1 is the previous period's actual demand. The term (At−1−Ft−1) represents the forecast error from the previous period. The smoothing constant, α, determines how much weight is given to this recent error to adjust the new forecast. The value of α must always be between 0 and 1 inclusive (0≤α≤1).
Ft=Ft−1+α(At−1−Ft−1)
03
Initial Forecast Assumption
When applying exponential smoothing, a starting forecast (F1) is required to begin the recursive calculation. If this initial forecast is not explicitly given in a problem, the standard convention is to set it equal to the actual demand of the first period (A1). Therefore, F1=A1.
04
Exponential smoothing update rule
Simple exponential smoothing updates the forecast by taking the previous forecast and adding a fraction of the previous forecast error. The fraction is the smoothing constant α, which controls the tradeoff between stability and responsiveness.
Ft=Ft−1+α(At−1−Ft−1)
05
Meaning of alpha
The parameter α is restricted to 0.0≤α≤1.0. Small values place little weight on the newest error and produce stronger smoothing; large values place more weight on the newest error and produce faster adjustment.
0.0≤α≤1.0
06
Endpoint case alpha = 0
If α=0, the update term disappears and the forecast remains equal to the previous forecast: Ft=Ft−1. This means the method does not reflect recent data and acts like very heavy smoothing toward an average.
Ft=Ft−1
07
Endpoint case alpha = 1
If α=1, the full previous error is added back, giving Ft=At−1. This is the naive forecast, because the next prediction is simply the most recent actual observation.
Ft=At−1
08
Choosing alpha for stable versus volatile demand
Use a lower α when demand is stable and you want the forecast to stay close to an average. Use a higher α when demand is volatile and you need the forecast to respond quickly to recent changes.
09
Objective: minimize forecast error
The practical goal of selecting α is to obtain the most accurate forecast possible. The lecture recommends trial and error on historical data and choosing the model that gives the lowest forecast error rather than relying on intuition.
10
Exponential smoothing update formula
The video defines the one-period-ahead exponential smoothing forecast as the previous forecast plus a fraction of the previous forecast error. This makes the new forecast move partway from the old forecast toward the latest actual observation.
Ft=Ft−1+α(At−1−Ft−1)
11
Meaning of the smoothing constant alpha
The parameter α controls the balance between smoothing and responsiveness. Smaller values produce a flatter, more averaged forecast; larger values make the forecast follow recent changes more quickly.
0.0≤α≤1.0
12
Endpoint case alpha = 0
When α=0, the error term is multiplied by zero, so the forecast never updates from the prior forecast. The slide states directly that the forecast does not reflect recent data.
Ft=Ft−1
13
Endpoint case alpha = 1
When α=1, the update cancels the previous forecast and leaves only the latest actual observation. The next forecast is exactly the most recent demand value.
Ft=At−1
14
Graphical comparison of alpha = 0.1 and alpha = 0.5
The graph overlays actual demand with two smoothed forecasts. The purple α=0.1 line is much flatter, while the green α=0.5 line tracks peaks and troughs more closely, visually demonstrating the smoothing-versus-responsiveness trade-off.
15
Car dealer worked example
Given a February forecast of 142, actual February demand of 153, and α=0.20, the March forecast is obtained by substituting into the exponential smoothing formula. The displayed setup leads to 144.2 cars, although the clip ends before the instructor says the answer aloud.
Ft=142+0.20(153−142)=144.2
16
Exponential Smoothing Formula
The exponential smoothing formula is used to forecast future demand based on past forecasts and actual demand. The formula is Ft=Ft−1+α(At−1−Ft−1), where Ft is the forecast for period t, Ft−1 is the forecast for period t-1, At−1 is the actual demand for period t-1, and α is the smoothing constant.
Ft=Ft−1+α(At−1−Ft−1)
17
Smoothing Constant
The smoothing constant, denoted by α, determines the weight given to the most recent actual demand versus the previous forecast. A lower α (closer to 0) results in a smoother forecast that reacts slowly to changes, while a higher α (closer to 1) results in a more responsive forecast that reacts quickly to changes.
18
Example Calculation
To forecast March demand given a February forecast of 142, actual February demand of 153, and a smoothing constant of 0.20, apply the formula: F_{March} = 142+0.20(153−142)=142+0.20(11)=142+2.2=144.2. Rounding to the nearest whole number gives a forecast of 144 cars.
FMarch=142+0.20(153−142)=144.2≈144
19
Exponential Smoothing Formula
Used to update forecasts based on past errors. The new forecast is the previous forecast adjusted by a fraction (α) of the difference between the actual value and the previous forecast.
Ft=Ft−1+α(At−1−Ft−1)
20
Worked Example: Car Demand
Given a previous forecast of 142, actual demand of 153, and α=0.20, the next forecast is calculated as 142+0.2(153−142)=144.2≈144.
Detailed learning notes
Explore conditions, steps and evidence. Supplementary explanations are labeled separately from content shown in the video.
Symbols · 23
Ft
Clear evidence
Shown in the video
Evidence
Audio
Observation
The speaker states, "F of t is your new forecast for period t."
Formula
Observation
Slide text defines Ft = New forecast for period t.
Symbol
Ft
Meaning
New forecast for period t
Domain
Real numbers representing demand or quantity
Ft−1
Clear evidence
Shown in the video
Evidence
Audio
Observation
The speaker states, "F t minus one is your previous period's forecast."
Formula
Observation
Slide text defines Ft−1 = Previous period's forecast.
Symbol
Ft−1
Meaning
Previous period's forecast
Domain
Real numbers representing demand or quantity
At−1
Clear evidence
Shown in the video
Evidence
Audio
Observation
The speaker states, "A t minus one is your previous period's actual demand."
Formula
Observation
Slide text defines At−1 = Previous period's actual demand.
Symbol
At−1
Meaning
Previous period's actual demand
Domain
Real numbers representing demand or quantity
α
Clear evidence
Shown in the video
Evidence
Audio
Observation
The speaker states, "your lowercase a that alpha on there is your smoothing constant. Your smoothing constant has to be between zero and one. Okay, it has to be between zero and one. It cannot be a negative number."
Formula
Observation
Slide text defines α = ("alpha") the smoothing constant (0≤α≤1).
Symbol
α
Meaning
Smoothing constant
Domain
0≤α≤1
(A - F)
Clear evidence
Shown in the video
Evidence
Audio
Observation
The speaker states, "And then A minus F, both uppercase, that's your error term. That's your actual minus forecast."
Formula
Observation
Slide text defines (A - F) = the error term (Actual - Forecast).
Symbol
(A - F)
Meaning
Error term (Actual - Forecast)
Domain
Real numbers
α
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide shows 0.0≤α≤1.0 and labels α as the smoothing constant.
Audio
Observation
Speaker repeatedly discusses choosing alpha closer to zero or closer to one.
Symbol
α
Meaning
Smoothing constant controlling how much weight is placed on recent forecast error.
Domain
Real interval with 0.0≤α≤1.0.
Ft
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide uses Ft in the recurrence Ft=Ft−1+α(At−1−Ft−1).
Symbol
Ft
Meaning
Forecast for period t produced by exponential smoothing.
Domain
Same units as demand or sales being forecast.
Ft−1
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide uses Ft−1 as the previous period's forecast in the recurrence.
Symbol
Ft−1
Meaning
Forecast from the immediately preceding period.
Domain
Same units as Ft.
At−1
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide uses At−1 in the term (At−1−Ft−1).
Symbol
At−1
Meaning
Actual demand or actual value observed in the previous period.
Domain
Same units as Ft and Ft−1.
α
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 shows the range 0.0≤α≤1.0 and labels it the smoothing constant.
Audio
Observation
The lecturer repeatedly refers to alpha as the smoothing constant and discusses values close to zero or one.
Symbol
α
Meaning
Smoothing constant controlling the weight given to the most recent forecast error.
Domain
0.0≤α≤1.0
Ft
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 and slide 4-4 use Ft in the exponential smoothing update formula.
Audio
Observation
In the example, the lecturer asks for the March demand forecast, corresponding to Ft when t is March.
Symbol
Ft
Meaning
Forecast for period t.
Domain
Real-valued forecast quantity; in the example, number of cars.
Ft−1
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 writes Ft−1 inside the update equation.
Formula
Observation
Slide 4-4 uses Ft−1=142 as the February forecast made in January.
Symbol
Ft−1
Meaning
Forecast for the immediately preceding period t-1.
Domain
Same units as Ft.
Knowledge points · 14
Definition of Exponential Smoothing
Clear evidence
Shown in the video
Evidence
Audio
Observation
The speaker states, "Exponential smoothing is a weighted moving average forecasting technique in which data points are weighted by an exponential function. The forecast smooths out the irregular functions in time."
Formula
Observation
Slide text reads: "Exponential Smoothing a weighted moving average forecasting technique in which data points are weighted by an exponential function" and "The forecast 'smooths out' the irregular fluctuations in the time series".
Definition
Explanation
Exponential smoothing is a quantitative forecasting method used in time series analysis. It is a type of weighted moving average where data points are assigned weights according to an exponential function, which helps to smooth out irregular fluctuations in the data.
Conditions
Applicable to time series data
Initial Forecast Assumption
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide text reads: "Note: If starting forecast is not given, assume F1=A1".
Method
Explanation
When applying exponential smoothing, if the starting forecast for the first period is not provided, it is standard practice to assume that the initial forecast is equal to the actual demand of the first period.
Conditions
Starting forecast is not given
Exponential smoothing update rule
Clear evidence
Shown in the video
Evidence
Formula
Observation
The slide displays Ft=Ft−1+α(At−1−Ft−1).
Audio
Observation
The lecture explains that changing alpha changes how strongly the forecast responds to recent error.
Formula
Explanation
The current forecast is updated from the previous forecast by adding a fraction of the previous forecast error. The fraction is the smoothing constant α.
Formula
Ft=Ft−1+α(At−1−Ft−1)
Conditions
0.0≤α≤1.0
Requires a previous forecast Ft−1 and a previous actual observation At−1.
Behavior when alpha equals zero
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide states: If α=0, then Ft=Ft−1+α(At−1−Ft−1)=Ft−1+0.
Audio
Observation
Speaker says that if alpha is close to zero, you smooth out more and get closer to an average.
Definition
Explanation
When α=0, the update adds nothing to the prior forecast, so the new forecast remains equal to the old forecast. In practical terms, the method becomes very slow to react to recent data and behaves like strong smoothing toward an average.
Formula
Ft=Ft−1
Conditions
Applies only when α=0.
Prerequisites
Exponential smoothing update rule
Behavior when alpha equals one
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide states: If α=1, then Ft=Ft−1+1(At−1−Ft−1)=At−1.
Audio
Observation
Speaker says that if alpha is closer to one, it is really close to your naive forecast, where you get close to the previous period's demand.
Definition
Explanation
When α=1, the forecast fully absorbs the previous error and becomes exactly the previous actual value. This is equivalent to a naive forecast that copies the most recent observation.
Formula
Ft=At−1
Conditions
Applies only when α=1.
Prerequisites
Exponential smoothing update rule
Choosing the smoothing constant
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide text says the closer alpha is to zero, the slower the forecast adjusts; the closer to one, the greater the responsiveness.
Audio
Observation
Speaker recommends low alpha when demand or sales are stable and higher alpha when there is more volatility.
Method
Explanation
Select a smaller α when the underlying demand is stable and you want stronger smoothing, and select a larger α when demand is volatile and you want the forecast to respond quickly to recent changes.
Conditions
Stable demand favors α near 0.
Volatile demand favors α near 1.
The final choice should be tested against historical accuracy.
Prerequisites
Behavior when alpha equals zero
Behavior when alpha equals one
Forecasting objective
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide states: The objective is to obtain the most accurate forecast no matter the technique.
Audio
Observation
Speaker says the goal is the lowest forecast error and that operations staff should use trial and error by changing alpha.
Method
Explanation
The purpose of tuning α is not aesthetic smoothing itself but achieving the most accurate forecast possible, usually by selecting the model that gives the lowest forecast error on available historical data.
Conditions
Requires historical data for evaluation.
Model comparison should use forecast error measures.
Prerequisites
Choosing the smoothing constant
Exponential smoothing update formula
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 displays Ft=Ft−1+α(At−1−Ft−1).
Formula
Observation
Slide 4-4 repeats the same formula under the example heading.
Formula
Explanation
The video presents the one-step exponential smoothing recursion as the prior forecast plus a fraction of the previous forecast error. The term (At−1−Ft−1) is the error from the last period, and α determines how much of that error is carried into the next forecast.
Formula
Ft=Ft−1+α(At−1−Ft−1)
Conditions
0.0≤α≤1.0
Requires a previous forecast Ft−1 and the actual value At−1 from the prior period.
Prerequisites
α
Ft
Ft−1
At−1
Effect of α=0
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 lists If α=0: Ft=Ft−1+0 and Ft=Ft−1.
Formula
Observation
Slide 4-2 adds the bullet 'The forecast does not reflect recent data'.
Definition
Explanation
When the smoothing constant is zero, the update formula collapses to Ft=Ft−1. The video states that this means the forecast does not reflect recent data, because the new actual observation receives no weight.
Formula
Ft=Ft−1
Conditions
α=0
Prerequisites
Exponential smoothing update formula
Effect of α=1
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 lists If α=1: Ft=Ft−1+1(At−1−Ft−1) and Ft=At−1.
Definition
Explanation
When the smoothing constant equals one, the update becomes Ft=At−1. The next forecast is exactly the most recent actual observation, so the model fully follows the latest data point.
Formula
Ft=At−1
Conditions
α=1
Prerequisites
Exponential smoothing update formula
Choosing the smoothing constant
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 states: 'The closer its value to zero, the slower the forecast will be to adjust to forecast errors (the greater the smoothing)' and 'The closer its value to one, the greater the responsiveness and the less the smoothing'.
Audio
Observation
The lecturer says the smoothing constant is a great way to reduce forecasting error, especially when there is not a lot of data because only the previous period's data is used.
Method
Explanation
The video explains a trade-off: smaller α gives stronger smoothing and slower adjustment to errors, while larger α gives greater responsiveness and weaker smoothing. It also states that the practical objective is to obtain the most accurate forecast, usually by selecting the model with the lowest forecast error.
Conditions
Applicable when using exponential smoothing for forecasting.
Prerequisites
Exponential smoothing update formula
Effect of α=0
Effect of α=1
Exponential Smoothing Formula
Clear evidence
Shown in the video
Evidence
Formula
Observation
The formula Ft=Ft−1+α(At−1−Ft−1) is displayed on the slide.
Audio
Observation
The speaker explains how to use the formula to calculate the March forecast.
Formula
Explanation
The exponential smoothing formula is used to forecast future demand based on past forecasts and actual demand. The formula is Ft=Ft−1+α(At−1−Ft−1), where Ft is the forecast for period t, Ft−1 is the forecast for period t-1, At−1 is the actual demand for period t-1, and α is the smoothing constant.
Formula
Ft=Ft−1+α(At−1−Ft−1)
Conditions
0<α<1
Claims and conditions · 3
Range of the smoothing constant
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide explicitly shows 0.0≤α≤1.0.
Proposition
Statement
For this exponential smoothing setup, the smoothing constant satisfies 0.0≤α≤1.0.
Hypotheses
Using the standard simple exponential smoothing formula shown on the slide.
Quantifiers
For the smoothing constant α in the displayed model.
Zero alpha ignores recent data
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide states that if α=0, then Ft=Ft−1 and the forecast does not reflect recent data.
Proposition
Statement
If α=0, then Ft=Ft−1, so the forecast does not reflect recent data.
Hypotheses
The update rule is Ft=Ft−1+α(At−1−Ft−1).
α=0.
Quantifiers
For all periods t under the stated update rule.
Alpha equals one gives the naive forecast
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide states that if α=1, then Ft=At−1.
Audio
Observation
Speaker identifies this case as being close to the naive forecast.
Proposition
Statement
If α=1, then Ft=At−1, which corresponds to a naive forecast using the previous period's actual demand.
Hypotheses
The update rule is Ft=Ft−1+α(At−1−Ft−1).
α=1.
Quantifiers
For all periods t under the stated update rule.
Derivations and proofs · 6
Derivation for alpha = 0
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide shows the substitution steps from Ft=Ft−1+α(At−1−Ft−1) to Ft=Ft−1+0 and then Ft=Ft−1.
Proof
Steps
Expression
Ft=Ft−1+α(At−1−Ft−1)
Explanation
Start from the general exponential smoothing update rule.
Justification
Given formula on the slide.
Shown in the video
Expression
Ft=Ft−1+0(At−1−Ft−1)
Explanation
Substitute α=0 into the update rule.
Justification
Case assumption α=0.
Shown in the video
Expression
Ft=Ft−1
Explanation
The error term is multiplied by zero, so no adjustment is made.
Justification
Arithmetic simplification.
Shown in the video
Conclusion
When α=0, the forecast stays fixed at the previous forecast and does not incorporate recent actual data.
Derivation for alpha = 1
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide shows the substitution steps from Ft=Ft−1+α(At−1−Ft−1) to Ft=Ft−1+1(At−1−Ft−1) and then Ft=At−1.
Proof
Steps
Expression
Ft=Ft−1+α(At−1−Ft−1)
Explanation
Start from the general exponential smoothing update rule.
Justification
Given formula on the slide.
Shown in the video
Expression
Ft=Ft−1+1(At−1−Ft−1)
Explanation
Substitute α=1 into the update rule.
Justification
Case assumption α=1.
Shown in the video
Expression
Ft=At−1
Explanation
The full previous error is added back, leaving exactly the previous actual value.
When α=1, exponential smoothing reduces to the naive forecast Ft=At−1.
Derivation of the α=0 special case
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 shows the substitution chain from Ft=Ft−1+α(At−1−Ft−1) to Ft=Ft−1+0 and then Ft=Ft−1 under If α=0.
Proof
Steps
Expression
Ft=Ft−1+α(At−1−Ft−1)
Explanation
Start from the general exponential smoothing update shown on the slide.
Justification
Given formula on slide 4-2.
Shown in the video
Expression
Ft=Ft−1+0(At−1−Ft−1)
Explanation
Substitute α=0 into the update formula.
Justification
Special-case assumption α=0.
Shown in the video
Expression
Ft=Ft−1
Explanation
The error term is multiplied by zero, so the forecast remains unchanged from the previous forecast.
Justification
Algebraic simplification.
Shown in the video
Conclusion
If α=0, the forecast does not incorporate the latest actual observation and stays equal to the previous forecast.
Derivation of the α=1 special case
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 shows the substitution chain from Ft=Ft−1+α(At−1−Ft−1) to Ft=Ft−1+1(At−1−Ft−1) and then Ft=At−1 under If α=1.
Proof
Steps
Expression
Ft=Ft−1+α(At−1−Ft−1)
Explanation
Start from the general exponential smoothing update shown on the slide.
Justification
Given formula on slide 4-2.
Shown in the video
Expression
Ft=Ft−1+1(At−1−Ft−1)
Explanation
Substitute α=1 into the update formula.
Justification
Special-case assumption α=1.
Shown in the video
Expression
Ft=At−1
Explanation
The previous forecast cancels out, leaving the most recent actual value as the new forecast.
Justification
Algebraic simplification.
Shown in the video
Conclusion
If α=1, the next forecast equals the latest actual observation.
Numerical derivation of the March forecast from the example data
Clear evidence
Derived from the video
Evidence
Formula
Observation
Slide 4-4 gives Ft−1=142, At−1=153, α=0.20, and asks for the March forecast using Ft=Ft−1+α(At−1−Ft−1).
Audio
Observation
The lecturer reads the same numerical setup aloud.
Uncertainties
The final numeric answer is not spoken before the clip ends.
Numerical verification
Steps
Expression
Ft=Ft−1+α(At−1−Ft−1)
Explanation
Use the exponential smoothing update formula shown on the example slide.
Justification
Formula given in the video.
Shown in the video
Expression
Ft=142+0.20(153−142)
Explanation
Substitute the February forecast 142, actual February demand 153, and smoothing constant 0.20.
Justification
Values stated in the problem text on slide 4-4.
Shown in the video
Expression
Ft=142+0.20(11)
Explanation
Compute the forecast error from the previous period.
Justification
Arithmetic simplification.
Derived from the video
Expression
Ft=142+2.2
Explanation
Multiply the error by the smoothing constant.
Justification
Arithmetic simplification.
Derived from the video
Expression
Ft=144.2
Explanation
Add the adjustment to the previous forecast to obtain the March forecast.
Justification
Arithmetic simplification.
Derived from the video
Conclusion
Using the data shown in the example, the March forecast computed from the displayed formula is 144.2 cars.
Derivation of March Forecast
Clear evidence
Shown in the video
Evidence
Audio
Observation
The speaker walks through the calculation step-by-step.
Formula
Observation
The calculation steps are displayed on the slide: March Fcst = F(Feb) + α[A(Feb) - F(Feb)] = 142+0.2[153−142]=142+2.2=144.2 ≈ 144 cars.
Numerical verification
Steps
Expression
Ft=Ft−1+α(At−1−Ft−1)
Explanation
Start with the general exponential smoothing formula.
Justification
Definition of exponential smoothing.
Shown in the video
Expression
FMarch=FFeb+0.20(AFeb−FFeb)
Explanation
Substitute the given values into the formula: F_{Feb} = 142, A_{Feb} = 153, and α=0.20.
Justification
Given values from the problem statement.
Shown in the video
Expression
FMarch=142+0.20(153−142)
Explanation
Perform the subtraction inside the parentheses.
Justification
Arithmetic operation.
Shown in the video
Expression
FMarch=142+0.20(11)
Explanation
Simplify the expression.
Justification
Arithmetic operation.
Shown in the video
Expression
FMarch=142+2.2
Explanation
Multiply 0.20 by 11.
Justification
Arithmetic operation.
Shown in the video
Expression
FMarch=144.2
Explanation
Add 142 and 2.2.
Justification
Arithmetic operation.
Shown in the video
Expression
FMarch≈144
Explanation
Round the result to the nearest whole number.
Justification
Practical application for forecasting car sales.
Shown in the video
Conclusion
The forecasted demand for March is approximately 144 cars.
Worked examples · 3
Car dealer exponential smoothing example
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-4 contains the full word problem and the update formula.
Audio
Observation
The lecturer reads: 'In January, a car dealer predicted February demand for 142 Ford Mustangs. Actual February demand was 153 cars. Using a smoothing constant chosen by management of an alpha of 0.2, the dealer wants to forecast March demand using the exponential smoothing model.'
Uncertainties
The clip ends before the instructor verbally states the final answer.
Problem
A car dealer predicted February demand for 142 Ford Mustangs. Actual February demand was 153 cars. With smoothing constant α=0.20, forecast March demand using exponential smoothing.
Given
Ft−1=142 (February forecast made in January)
At−1=153 (actual February demand)
α=0.20
Goal
Compute Ft, the forecast for March demand.
Steps
Expression
Ft=Ft−1+α(At−1−Ft−1)
Explanation
Write the exponential smoothing update formula shown on the slide.
Justification
Given model in the video.
Shown in the video
Expression
Ft=142+0.20(153−142)
Explanation
Insert the numerical values from the problem statement.
Justification
Direct substitution from the given data.
Shown in the video
Expression
Ft=144.2
Explanation
Evaluate the expression to obtain the March forecast.
Justification
Arithmetic simplification.
Derived from the video
Answer
144.2 cars
Verification
The result lies between the previous forecast 142 and the actual demand 153, which matches the interpretation that α=0.20 moves the forecast partway toward the latest observation.
Car Dealer Demand Forecasting
Clear evidence
Shown in the video
Evidence
Audio
Observation
The speaker presents the problem and solves it.
Formula
Observation
The problem statement and solution steps are displayed on the slide.
Problem
In January, a car dealer predicted February demand for 142 Ford Mustangs. Actual February demand was 153 cars. Using a smoothing constant chosen by management of α=0.20, the dealer wants to forecast March demand using the exponential smoothing model.
Given
Predicted February demand (F_{Feb}) = 142
Actual February demand (A_{Feb}) = 153
Smoothing constant (α) = 0.20
Goal
Forecast March demand (F_{March})
Steps
Expression
FMarch=FFeb+α(AFeb−FFeb)
Explanation
Apply the exponential smoothing formula.
Justification
Definition of the model.
Shown in the video
Expression
FMarch=142+0.20(153−142)
Explanation
Substitute the given values.
Justification
Problem statement.
Shown in the video
Expression
FMarch=142+0.20(11)
Explanation
Calculate the difference between actual and predicted demand.
Justification
Arithmetic.
Shown in the video
Expression
FMarch=142+2.2
Explanation
Multiply the difference by the smoothing constant.
Justification
Arithmetic.
Shown in the video
Expression
FMarch=144.2
Explanation
Add the result to the previous forecast.
Justification
Arithmetic.
Shown in the video
Expression
FMarch≈144
Explanation
Round to the nearest whole number.
Justification
Practical context.
Shown in the video
Answer
144 cars
Verification
The calculation steps are shown on the slide and explained by the speaker.
Car Dealer Demand Forecast
Clear evidence
Shown in the video
Evidence
Formula
Observation
March Fcst = 142+0.2[153−142]=144.2≈144 cars
Problem
In January, a car dealer predicted February demand for 142 Ford Mustangs. Actual February demand was 153 cars. Using a smoothing constant chosen by management of α=0.20, the dealer wants to forecast March demand using the exponential smoothing model.
Given
Previous forecast F(Feb)=142
Previous actual demand A(Feb)=153
Smoothing constant α=0.20
Goal
Forecast March demand
Steps
Expression
F(Mar)=F(Feb)+α[A(Feb)−F(Feb)]
Explanation
Substitute the given values into the exponential smoothing formula.
Justification
Definition of exponential smoothing
Shown in the video
Expression
=142+0.2[153−142]
Explanation
Calculate the difference between actual and forecasted demand.
Justification
Arithmetic substitution
Shown in the video
Expression
=142+2.2
Explanation
Multiply the difference by the smoothing constant.
Justification
Arithmetic calculation
Shown in the video
Expression
=144.2≈144 cars
Explanation
Add the adjustment to the previous forecast and round to the nearest whole number.
Justification
Arithmetic calculation and rounding
Shown in the video
Answer
144 cars
Verification
The calculation follows the standard exponential smoothing procedure shown on the slide.
Visual events · 9
Textbook Scope Clarification
Clear evidence
Shown in the video
Evidence
Animation
Observation
A yellow text box appears at the bottom of the slide containing the text: "You do not need to learn Exponential Smoothing with Trend Adjustment pg 120".
Audio
Observation
The speaker says, "you do not need to learn exponential smoothing with trend adjustment right now in the textbook that is page 120 I believe you do not need to know that so we're just going to go over exponential smoothing but you don't have to learn how to do it with trend adjustment."
Objects
Yellow text box
Changes
Text box appears on screen
Invariants
Main slide content remains unchanged
Interpretation
The visual update serves to clarify the scope of the lesson, explicitly stating that students are not required to learn the trend-adjusted version of exponential smoothing from the specified textbook page.
Slide change from definition to parameter effects
Clear evidence
Shown in the video
Evidence
Diagram
Observation
The video begins on a slide titled 'Exponential Smoothing' and then changes to a slide titled 'Effect of the Smoothing Constant'.
Audio
Observation
The speaker transitions verbally into discussing the effect of alpha.
Uncertainties
The exact transition second is approximate because the sampled frames do not pinpoint the cut more finely than about one second.
Objects
Title slide 'Exponential Smoothing'
Second slide 'Effect of the Smoothing Constant'
Presenter inset window
Changes
The main slide content switches from the general formula and variable definitions to the special cases α=0 and α=1 plus guidance on choosing α.
Invariants
The presenter remains visible in the upper-right inset.
The lecture continues without a scene change away from slides.
Interpretation
The visual progression mirrors the conceptual progression from the general exponential smoothing equation to the role of the smoothing constant within that equation.
Static summary slide on the effect of the smoothing constant
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Slide 4-2 titled 'Effect of the Smoothing Constant' shows the range 0.0≤α≤1.0, the general formula, the two endpoint cases, and bullets about choosing α.
Objects
Title text
General formula Ft=Ft−1+α(At−1−Ft−1)
Case α=0
Case α=1
Bullet list on choosing α
Changes
No animation occurs during this interval; the slide remains static while the lecturer speaks.
Invariants
The displayed formula and endpoint interpretations remain fixed throughout 0-7 seconds.
Interpretation
This slide establishes the model and the extreme behaviors of the smoothing constant before the graphical comparison.
Actual demand curve alone
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Slide 4-3 first shows only a blue line labeled 'Actual demand' on axes Demand versus Quarter.
Audio
Observation
The lecturer describes the pattern as going down, then up, then down again, with a slight overall upward trend.
Uncertainties
Exact plotted values are not printed, so only qualitative shape can be confirmed.
Objects
Blue line labeled 'Actual demand'
Vertical axis Demand
Horizontal axis Quarter
Changes
From 7 to about 31 seconds, only the actual demand series is visible.
Invariants
The axes and the blue actual-demand path remain unchanged during this interval.
Interpretation
The graph introduces the raw time series that the later smoothed forecasts will try to track.
Addition of the α=0.1 forecast line
Clear evidence
Shown in the video
Evidence
Animation
Observation
Around 31 seconds, a purple line labeled 'α=0.1' appears beneath the actual demand curve.
Audio
Observation
The lecturer says that if you pick an alpha close to zero, all it's doing is taking this average, and you're smoothing it out.
Objects
Blue actual demand line
Purple forecast line labeled α=0.1
Changes
A second curve is added to the graph.
The new purple curve is visibly flatter than the blue actual-demand curve.
Invariants
The blue actual-demand curve remains unchanged.
The axes remain unchanged.
Interpretation
The visual comparison shows that a small smoothing constant produces a heavily smoothed forecast that lags behind sharp changes in actual demand.
Addition of the α=0.5 forecast line
Clear evidence
Shown in the video
Evidence
Animation
Observation
Around 52 seconds, a green line labeled 'α=0.5' appears between the blue actual-demand line and the purple α=0.1 line.
Audio
Observation
The lecturer says that with alpha closer to one, it would be more responsive to the changes; it went down faster and then up faster.
Objects
Blue actual demand line
Purple α=0.1 line
Green α=0.5 line
Changes
A third curve is added.
The green curve follows the peaks and troughs of the blue curve more closely than the purple curve.
Invariants
The blue actual-demand curve and the purple α=0.1 curve remain unchanged after the green curve appears.
Interpretation
The three-line comparison demonstrates the responsiveness-smoothing trade-off: larger α tracks recent changes more quickly.
Worked-example slide
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Slide 4-4 titled 'Exponential Smoothing Example' shows the word problem and the formula Ft=Ft−1+α(At−1−Ft−1).
Objects
Problem text about a car dealer
Formula Ft=Ft−1+α(At−1−Ft−1)
Changes
The presentation switches from the comparative graph to a text-and-formula example slide.
Invariants
The slide content remains static through the end of the clip.
Interpretation
The lecture moves from qualitative comparison to a concrete numerical application of the same formula.
Presentation Slide
Clear evidence
Shown in the video
Evidence
Diagram
Observation
A presentation slide titled 'Exponential Smoothing Example' is displayed throughout the video. It contains the problem statement, the formula, and the step-by-step calculation.
Objects
Text
Formula
Calculation steps
Changes
The calculation steps appear sequentially on the slide as the speaker explains them.
Invariants
The problem statement and the general formula remain visible throughout the video.
Interpretation
The slide provides a visual aid for the speaker's explanation of the exponential smoothing method and its application to a specific forecasting problem.
Exponential Smoothing Example Slide
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Slide titled 'Exponential Smoothing Example' showing problem statement, formula, and step-by-step calculation highlighted in yellow.
Objects
Problem text
Formula Ft=Ft−1+α(At−1−Ft−1)
Variable definitions
Calculation steps
Invariants
The slide content remains static throughout the 3-second clip.
Interpretation
The visual presents a complete worked example of applying the exponential smoothing formula to forecast car demand.
Misconceptions · 4
Larger alpha is not automatically better
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide contrasts low alpha giving greater smoothing with high alpha giving greater responsiveness.
Audio
Observation
Speaker says low alpha suits stable demand and high alpha suits volatile demand.
Misconception
A common mistake is to think that making α larger always improves the forecast because it reacts faster.
Clarification
A larger α increases responsiveness but reduces smoothing. It is appropriate when demand is volatile, while a smaller α is preferable when demand is stable and you want the forecast to stay closer to an average.
Do not choose alpha only by intuition
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide says the objective is the most accurate forecast and that one generally selects the model with the lowest forecast error.
Audio
Observation
Speaker warns that without historical data we do not know whether a chosen alpha is truly good.
Misconception
Another mistake is to pick α just because it feels reasonable or because one month looked good.
Clarification
The lecture emphasizes using historical data and trial-and-error evaluation so that the selected α minimizes forecast error rather than relying on anecdote.
Misreading small α as faster adaptation
Clear evidence
Shown in the video
Evidence
Audio
Observation
The lecturer contrasts alpha close to zero, which is 'pretty much an average', with alpha closer to one, which is 'more responsive to the changes'.
Animation
Observation
The purple α=0.1 line stays much flatter than the green α=0.5 line.
Misconception
One might think a smaller smoothing constant makes the forecast react more quickly to new data.
Clarification
The video shows and states the opposite: smaller α gives greater smoothing and slower adjustment, while larger α gives greater responsiveness.
Assuming α=0 still incorporates the latest observation
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 explicitly says for α=0 that 'The forecast does not reflect recent data'.
Misconception
Because the formula contains At−1, one might assume the latest actual value always affects the next forecast.
Clarification
When α=0, the error term is multiplied by zero, so the latest actual observation has no effect and Ft=Ft−1.
Concept relations · 12
Exponential smoothing update rule → Behavior when alpha equals zero
Clear evidence
Shown in the video
Evidence
Formula
Observation
The slide derives Ft=Ft−1 directly from the general update rule by setting α=0.
Special case
Explanation
The α=0 behavior is a direct special case of the general exponential smoothing formula.
Exponential smoothing update rule → Behavior when alpha equals one
Clear evidence
Shown in the video
Evidence
Formula
Observation
The slide derives Ft=At−1 directly from the general update rule by setting α=1.
Special case
Explanation
The α=1 behavior is also a direct special case of the same general formula.
Behavior when alpha equals one → Exponential smoothing update rule
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide shows Ft=At−1 when α=1.
Audio
Observation
Speaker calls this the naive forecast.
Equivalent
Explanation
Within this model, setting α=1 makes exponential smoothing equivalent to the naive forecast that copies the last actual observation.
Choosing the smoothing constant → Exponential smoothing update rule
Clear evidence
Shown in the video
Evidence
Formula
Observation
The guidance on choosing alpha is presented under the heading 'Effect of the Smoothing Constant' alongside the update formula.
Application
Explanation
The method for selecting α is applied directly to the exponential smoothing update rule to control responsiveness versus smoothing.
Forecasting objective → Choosing the smoothing constant
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide links the choice of alpha to obtaining the most accurate forecast and the lowest forecast error.
Prerequisite
Explanation
Understanding that the objective is lowest forecast error motivates why one tunes α instead of choosing it arbitrarily.
Effect of α=0 → Exponential smoothing update formula
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 derives Ft=Ft−1 directly from the general update by setting α=0.
Special case
Explanation
The α=0 behavior is a direct special case of the general exponential smoothing recursion.
Effect of α=1 → Exponential smoothing update formula
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 derives Ft=At−1 directly from the general update by setting α=1.
Special case
Explanation
The α=1 behavior is also a direct special case of the general exponential smoothing recursion.
Choosing the smoothing constant → Exponential smoothing update formula
Clear evidence
Shown in the video
Evidence
Formula
Observation
The bullets on choosing α interpret the parameter inside the displayed update formula.
Application
Explanation
The guidance on selecting α applies directly to the exponential smoothing update formula shown on the same slide.
Car dealer exponential smoothing example → Exponential smoothing update formula
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-4 places the numerical car-dealer problem above the same formula Ft=Ft−1+α(At−1−Ft−1).
Application
Explanation
The worked example is a direct numerical application of the exponential smoothing formula introduced earlier.
Choosing the smoothing constant → Addition of the α=0.5 forecast line
Clear evidence
Shown in the video
Evidence
Animation
Observation
The graph adds α=0.1 and α=0.5 curves to compare smoothing versus responsiveness.
Audio
Observation
The lecturer uses these curves to explain the effect of picking alpha close to zero versus closer to one.
Application
Explanation
The multi-curve graph visually applies the rule for choosing α by showing how different values affect tracking of actual demand.
Smoothing Constant → Exponential Smoothing Formula
Clear evidence
Shown in the video
Evidence
Audio
Observation
The speaker explains that a lower α results in a forecast closer to the previous forecast, while a higher α results in a forecast closer to the actual demand.
Application
Explanation
The smoothing constant α is a parameter in the exponential smoothing formula that determines the weight given to the most recent actual demand versus the previous forecast.
Exponential Smoothing Formula → Car Dealer Demand Forecast
Clear evidence
Shown in the video
Evidence
Diagram
Observation
The slide shows the general formula followed immediately by its application to specific numbers.
Application
Explanation
The car dealer example demonstrates the practical application of the exponential smoothing formula.
Find an answer · 15
What is the formula for exponential smoothing and what do its variables represent?
Clear evidence
Shown in the video
Evidence
Audio
Observation
The speaker explains the formula and its variables.
Formula
Observation
The formula Ft=Ft−1+α(At−1−Ft−1) is displayed.
Knowledge points
Definition of Exponential Smoothing
How should I handle the initial forecast if it is not given in an exponential smoothing problem?
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide text reads: "Note: If starting forecast is not given, assume F1=A1".
Knowledge points
Initial Forecast Assumption
What does the smoothing constant alpha do in exponential smoothing?
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide defines alpha as the smoothing constant and shows its range.
Knowledge points
Exponential smoothing update rule
Choosing the smoothing constant
Why does alpha equal to zero make the forecast ignore recent data?
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide explicitly treats the case α=0.
Knowledge points
Behavior when alpha equals zero
Derivation for alpha = 0
How is exponential smoothing related to the naive forecast when alpha is 1?
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide explicitly treats the case α=1 and the speaker names it the naive forecast.
Knowledge points
Behavior when alpha equals one
Derivation for alpha = 1
s108-rel-naive-equivalence
Should I choose a larger or smaller alpha when demand is volatile?
Clear evidence
Shown in the video
Evidence
Audio
Observation
Speaker contrasts stable demand with volatile demand when discussing alpha selection.
Knowledge points
Choosing the smoothing constant
Larger alpha is not automatically better
What criterion should determine the best smoothing constant?
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide states that the objective is the most accurate forecast and the lowest forecast error.
Knowledge points
Forecasting objective
Do not choose alpha only by intuition
What does the smoothing constant alpha do in exponential smoothing?
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slides and graph both focus on the role of α.
Audio
Observation
The lecturer explains smoothing versus responsiveness.
Knowledge points
Exponential smoothing update formula
Choosing the smoothing constant
Addition of the α=0.1 forecast line
Addition of the α=0.5 forecast line
Why does alpha equal to zero make the forecast ignore recent data?
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 explicitly lists the α=0 case.
Knowledge points
Effect of α=0
Derivation of the α=0 special case
Assuming α=0 still incorporates the latest observation
What happens to the exponential smoothing forecast when alpha equals one?
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-2 explicitly lists the α=1 case.
Knowledge points
Effect of α=1
Derivation of the α=1 special case
How does a smaller alpha differ from a larger alpha on a demand graph?
Clear evidence
Shown in the video
Evidence
Animation
Observation
The graph compares purple α=0.1 and green α=0.5 against blue actual demand.
Audio
Observation
The lecturer says smaller alpha smooths more and larger alpha is more responsive.
Knowledge points
Choosing the smoothing constant
Addition of the α=0.1 forecast line
Addition of the α=0.5 forecast line
Misreading small α as faster adaptation
How do you compute the March forecast from February forecast 142, actual 153, and alpha 0.20?
Clear evidence
Shown in the video
Evidence
Formula
Observation
Slide 4-4 provides all inputs needed to compute the March forecast.
Uncertainties
The spoken solution is absent in this clip.
Knowledge points
Car dealer exponential smoothing example
Numerical derivation of the March forecast from the example data
Exponential smoothing update formula
Coverage and review notes
Covered · Introduction to exponential smoothing as a quantitative time series forecasting method.
Covered · Formal definition of exponential smoothing as a weighted moving average technique.
Covered · Detailed explanation of the exponential smoothing formula and its variables.
Covered · Clarification that exponential smoothing with trend adjustment is not required for this lesson.
Covered · The entire clip consists of a spoken lecture over two slides introducing exponential smoothing and analyzing the effect of the smoothing constant alpha, including the endpoint cases alpha = 0 and alpha = 1 and the practical rule for choosing alpha to minimize forecast error.
Covered · Static slide introducing the formula, endpoint cases, and selection guidance for alpha.
Covered · Graph shows only the actual demand series while the lecturer describes its up-down pattern.
Covered · Purple alpha=0.1 curve is added to illustrate strong smoothing.
Covered · Green alpha=0.5 curve is added to illustrate greater responsiveness.
Covered · Worked numerical example slide is shown and read aloud; the clip ends before the instructor states the final answer.
Covered · The entire video covers the explanation and application of the exponential smoothing formula.
Covered · Static slide with audio fragment covering the full duration.