Reviewed learning material · Video analysis · EnglishRead the full overview
This video demonstrates how to explore and forecast a single time series using seasonal ARIMA models in JMP. Using the 'Steel Shipments' dataset, it shows how to set up the analysis, interpret autocorrelation (ACF) and partial autocorrelation (PACF) plots to suggest model orders, fit multiple seasonal ARIMA specifications, and compare their goodness-of-fit using information criteria like AIC and SBC to select the best model.
This 67-second JMP screencast demonstrates the ARIMA modeling report for “Time Series Steel Shipments.” It shows how to open ARIMA Model Group to specify ranges for ordinary and seasonal ARIMA parameters, browse graph-based diagnostics such as variogram, spectral density, difference, and lag plot, and export or submit a fitted model to SAS PROC ARIMA. The narration then states that ARIMA requires stationarity, recommends differencing for trend and logarithms for non-stationary variance, and notes that transfer functions can be used for forecasting with input variables only if those inputs were specified during initial model setup.
Use the learning inspector for key ideas and moments, or open the reading tabs for the complete notes.
Generated from the video's visuals and explanation; not verbatim speech.
The video begins by introducing the 'Steel Shipments' dataset, which contains monthly time series data. The analyst navigates to the Analyze > Modeling > Time Series menu in the JMP software to initiate the exploration.
In the launch dialog, the 'Steel Shipments' column is assigned to the Y, Time Series role, and the 'Date' column is assigned to the X, Time ID role. The speaker notes that the data must be sorted by time and evenly spaced for valid analysis.
Upon clicking OK, JMP generates the basic time series output. This includes a scatterplot of the series over time, alongside Autocorrelation Function (ACF) and Partial Autocorrelation Function (PACF) plots. These diagnostic plots reveal significant correlations at lag 1 and lag 12, suggesting the need for a model with both non-seasonal autoregressive (AR) terms and seasonal AR terms.
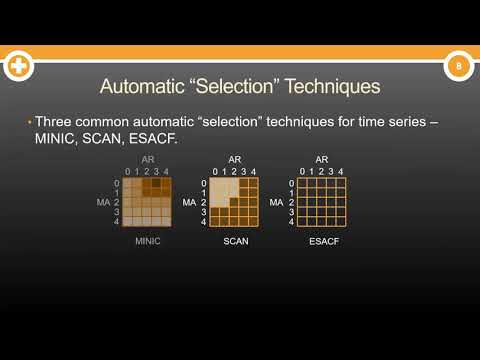
Guided by the ACF and PACF diagnostics, the analyst accesses the red triangle menu and selects 'Seasonal ARIMA'. In the specification dialog, they set the non-seasonal autoregressive order (p) to 2 and the seasonal autoregressive order (P) to 1, with the periods per season set to 12. This defines the first candidate model: ARIMA(2,0,0)(1,0,0)12.
After estimating the first model, the output displays parameter estimates, forecast plots, and residual diagnostics. The analyst expands the 'Residuals' section to inspect the ACF and PACF of the residuals, checking whether the model has adequately captured the data's structure or if further refinement is necessary.
To improve the fit, a second seasonal ARIMA model is requested. This time, in addition to p=2 and P=1, the analyst specifies a non-seasonal moving average order (q) of 3. This creates a more complex candidate model: ARIMA(2,0,3)(1,0,0)12.
Once the second model is estimated, JMP automatically populates the 'Model Comparison' report. The analyst expands this table to view side-by-side fit statistics for both models, specifically focusing on the Akaike Information Criterion (AIC) and the Schwarz Bayesian Criterion (SBC).
By comparing the numerical values in the Model Comparison table, it is evident that the second model (ARIMA(2,0,3)(1,0,0)12) yields lower AIC and SBC scores than the first model. Since lower values in these information criteria indicate a better trade-off between goodness-of-fit and model complexity, the second model is concluded to be the superior choice for forecasting the steel shipments.
The clip opens on a JMP report titled “Time Series Steel Shipments,” with a fitted model labeled “Seasonal ARIMA(2, 0, 0)(1, 0, 0)12.” The narration explains that multiple ARIMA and seasonal ARIMA candidates can be fit simultaneously by choosing ARIMA Model Group from the red-triangle menu.
When the “Specify ARIMA Model” dialog appears, the visible fields separate ordinary ARIMA orders p,d,q from seasonal ARIMA orders P,D,Q and the seasonal period, shown as 12. The dialog also displays a confidence level of 0.95 and checked options for Intercept and Constrain fit, illustrating that the software is set up to search over a family of models rather than just one fixed specification.
The next segment shifts from model estimation to diagnostics. From the top red-triangle Graph menu, the cursor highlights variogram, spectral density, difference, and lag plot options. These items are presented as supplementary views for examining time-series structure, dependence, and the effect of transformations or differencing.
The lower red-triangle menu for the fitted model shows how results can be exported or reused. The narration states that one can save the prediction formula, create a SAS job, or submit the ARIMA model to SAS using PROC ARIMA. A tooltip confirms that submission opens a SAS window and runs the analysis in PROC ARIMA.
The final conceptual portion states a modeling prerequisite: ARIMA models require the time series to be stationary. The speaker then gives two common remedies. If the series has trend over time, differencing is said to remove the trend. If the series has non-stationary variance, taking the logarithm of the series may help stabilize it.
Finally, the clip introduces transfer functions for forecasting with input variables. The key condition is explicit: those input variables must already have been specified when the model was first set up. The closing line directs viewers to JMP Help and the book Specialized Models for more information on time series and ARIMA models.
Knowledge cards
01
Setting Up Time Series Analysis in JMP
To analyze a time series in JMP, navigate to Analyze > Modeling > Time Series. Assign your target variable to the 'Y, Time Series' role and your temporal index to the 'X, Time ID' role. Ensure your data is sorted chronologically and evenly spaced; if the Time ID is omitted, the software assumes equal spacing between observations.
02
Interpreting ACF and PACF Plots
Autocorrelation Function (ACF) and Partial Autocorrelation Function (PACF) plots are essential diagnostic tools for identifying the orders of Autoregressive (AR) and Moving Average (MA) components in an ARIMA model. Significant spikes at specific lags indicate the presence of these components. For seasonal data, look for spikes at multiples of the seasonal period (e.g., lag 12 for monthly data) to identify seasonal AR or MA terms.
03
Specifying a Seasonal ARIMA Model
A Seasonal ARIMA model is denoted as ARIMA(p,d,q)(P,D,Q)s. The lowercase parameters (p, d, q) control the non-seasonal autoregressive order, differencing order, and moving average order, respectively. The uppercase parameters (P, D, Q) control the corresponding seasonal components. The parameter 's' represents the number of periods in a full seasonal cycle (e.g., s=12 for monthly data).
ARIMA(p,d,q)(P,D,Q)s
04
Evaluating Model Adequacy via Residuals
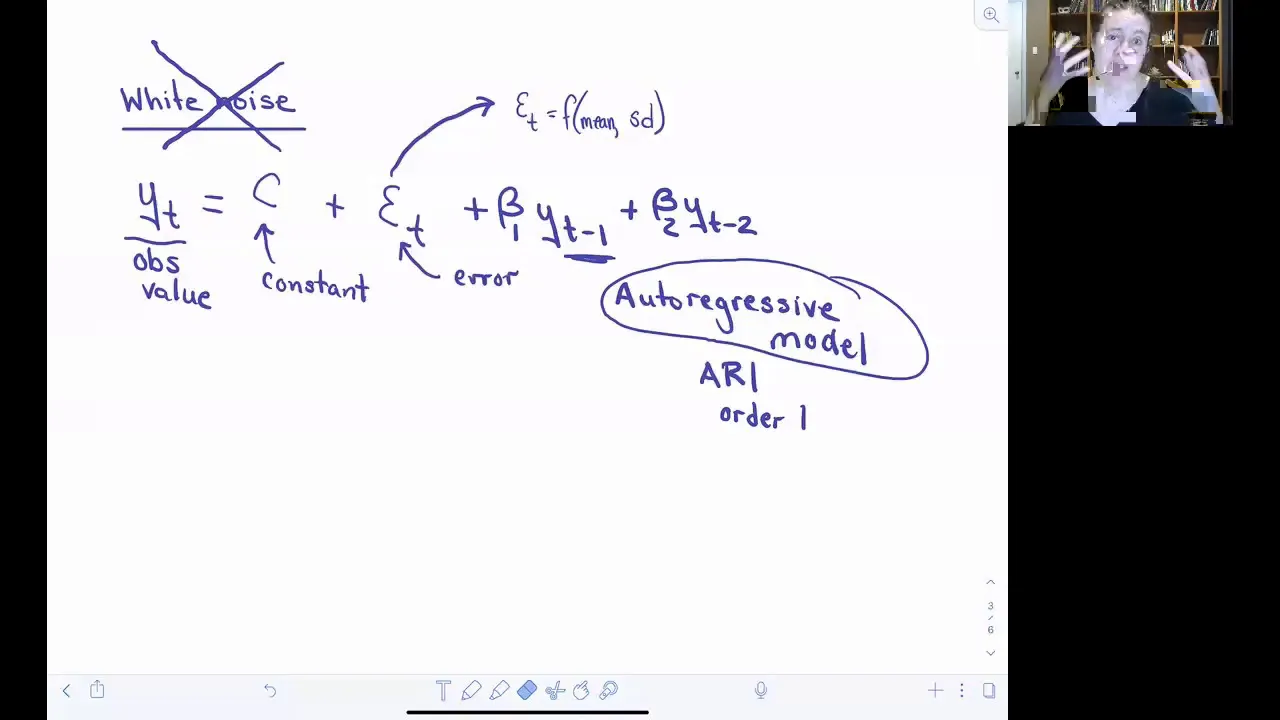
After fitting an ARIMA model, it is crucial to examine the residual diagnostics. Expanding the 'Residuals' section in the output reveals the ACF, PACF, and Ljung-Box statistics of the residuals. If the residuals resemble white noise (i.e., no significant autocorrelation), the model has adequately captured the underlying structure of the time series. Otherwise, a different model specification may be required.
05
Comparing ARIMA Models using AIC and SBC
When multiple ARIMA models are fitted to the same dataset, information criteria such as the Akaike Information Criterion (AIC) and the Schwarz Bayesian Criterion (SBC) are used to select the best model. Both metrics balance goodness-of-fit against model complexity, penalizing models with too many parameters. A lower AIC or SBC value indicates a preferable model.
06
ARIMA Model Group for simultaneous fitting
JMP can fit a range of ARIMA and seasonal ARIMA models at once through the ARIMA Model Group command under the red triangle. This turns model building into a search over candidate specifications rather than a single manual fit.
07
Specify ARIMA Model dialog parameters
The dialog exposes ordinary ARIMA orders p,d,q, seasonal ARIMA orders P,D,Q, and the seasonal period (shown as 12). It also includes Confidence Intervals set to 0.95 and options for Intercept and Constrain fit.
08
Graph diagnostics for time-series reports
From the top red-triangle Graph menu, the report offers variogram, spectral density, difference, and lag plot views. These diagnostics help inspect dependence, periodicity, trend removal, and bivariate time-series relationships.
09
Exporting a fitted ARIMA model
For any fitted model, the lower red-triangle menu allows saving the prediction formula, creating a SAS job, or submitting the analysis to SAS using PROC ARIMA. This connects the interactive fit to reproducible external SAS workflows.
10
Stationarity is required for ARIMA
The narration states that ARIMA models require the time series to be stationary. This is presented as a prerequisite before fitting, not as an optional diagnostic refinement.
11
Differencing removes trend
If the series has a trend over time, the clip says differencing will remove the trend. This corresponds to the d term in the ARIMA specification and is framed as a route toward stationarity.
12
Log transform for non-stationary variance
When the time series has non-stationary variance, taking the log of the series may be helpful. The video presents this as a variance-stabilizing transformation rather than a trend-removal method.
13
Transfer functions need pre-specified inputs
Transfer functions can be used to forecast with input variables, but only if those input variables were specified when the model was first set up. The clip emphasizes this as a necessary condition for using the Transfer Function option.
14
Further ARIMA references in JMP
For more information on time series and ARIMA models, the video directs users to search for ARIMA in JMP Help or consult the book Specialized Models.
Detailed learning notes
Explore conditions, steps and evidence. Supplementary explanations are labeled separately from content shown in the video.
Symbols · 40
Steel Shipments
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Column header 'Steel Shipments' in the data table.
Audio
Observation
Speaker says 'I'm using the steel shipments data set' and 'specify Steel Shipments as my time series'.
Symbol
Steel Shipments
Meaning
The dependent variable representing the time series of monthly steel shipments.
Domain
Positive real numbers (counts or volumes of shipments).
Date
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Column header 'Date' in the data table.
Audio
Observation
Speaker says 'and Date as my time ID'.
Symbol
Date
Meaning
The independent variable representing the time index for each observation.
Domain
Dates (monthly intervals from 01/01/1984 to 12/01/1991).
p
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Label 'p, Autoregressive Order' in the Seasonal ARIMA Specification dialog.
Audio
Observation
Speaker says 'specify two for the autoregressive order of ARIMA'.
Symbol
p
Meaning
The order of the non-seasonal autoregressive component in an ARIMA model.
Domain
Non-negative integers.
d
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Label 'd, Differencing Order' in the Seasonal ARIMA Specification dialog.
Symbol
d
Meaning
The order of non-seasonal differencing applied to the time series.
Domain
Non-negative integers.
q
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Label 'q, Moving Average Order' in the Seasonal ARIMA Specification dialog.
Audio
Observation
Speaker says 'three for q, the moving average order' at 94s.
Symbol
q
Meaning
The order of the non-seasonal moving average component in an ARIMA model.
Domain
Non-negative integers.
P
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Label 'P, Autoregressive Order' under Seasonal ARIMA in the specification dialog.
Audio
Observation
Speaker says 'one as the autoregressive order of seasonal ARIMA'.
Symbol
P
Meaning
The order of the seasonal autoregressive component in a seasonal ARIMA model.
Domain
Non-negative integers.
D
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Label 'D, Differencing Order' under Seasonal ARIMA in the specification dialog.
Symbol
D
Meaning
The order of seasonal differencing applied to the time series.
Domain
Non-negative integers.
Q
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Label 'Q, Moving Average Order' under Seasonal ARIMA in the specification dialog.
Symbol
Q
Meaning
The order of the seasonal moving average component in a seasonal ARIMA model.
Domain
Non-negative integers.
s
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Label 'Periods Per Season' in the Seasonal ARIMA Specification dialog, set to 12.
Symbol
s
Meaning
The number of periods that make up one full seasonal cycle.
Domain
Positive integers.
AIC
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Column header 'AIC' in the Model Comparison table.
Audio
Observation
Speaker mentions 'criteria such as AIC and SBC'.
Symbol
AIC
Meaning
Akaike Information Criterion, a measure used for model selection that penalizes model complexity.
Domain
Real numbers (lower is better).
SBC
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Column header 'SBC' in the Model Comparison table.
Audio
Observation
Speaker mentions 'criteria such as AIC and SBC'.
Symbol
SBC
Meaning
Schwarz Bayesian Criterion (also known as BIC), a measure used for model selection with a stronger penalty for complexity than AIC.
Domain
Real numbers (lower is better).
ARIMA
Clear evidence
Shown in the video
Evidence
Audio
Observation
The narration repeatedly names “ARIMA and seasonal ARIMA models.”
Diagram
Observation
The report title reads “Model: Seasonal ARIMA(2, 0, 0)(1, 0, 0)12”.
Symbol
ARIMA
Meaning
AutoRegressive Integrated Moving Average time-series model class used for forecasting a single series.
Domain
Time-series modeling; the video states the series must be stationary.
Knowledge points · 12
Seasonal ARIMA Model
Clear evidence
Shown in the video
Evidence
Audio
Observation
Speaker says 'To request the seasonal ARIMA, I'll go to the top red triangle and pick seasonal ARIMA.'
Diagram
Observation
The 'Seasonal ARIMA Specification' dialog box is shown with fields for p, d, q, P, D, Q, and Periods Per Season.
Definition
Explanation
A Seasonal ARIMA model extends the standard ARIMA model to capture seasonal patterns in time series data. It includes both non-seasonal parameters (p, d, q) and seasonal parameters (P, D, Q) along with the number of periods per season (s). The general notation is ARIMA(p,d,q)(P,D,Q)s.
Formula
ARIMA(p,d,q)(P,D,Q)s
Conditions
Time series data must be sorted by time and evenly spaced.
Requires specifying the seasonal period (e.g., 12 for monthly data).
Diagnosing ARIMA Orders via ACF and PACF
Clear evidence
Shown in the video
Evidence
Audio
Observation
Speaker says 'The autocorrelation and partial autocorrelation plots suggest an ARIMA model with a seasonal component of AR1 and a non-seasonal component of AR2.'
Diagram
Observation
Basic Time Series output showing ACF and PACF plots with significant spikes at lag 1 and lag 12.
Method
Explanation
The Autocorrelation Function (ACF) and Partial Autocorrelation Function (PACF) plots are used to identify the appropriate orders for the autoregressive (AR) and moving average (MA) components of an ARIMA model. Significant spikes at specific lags in these plots indicate the presence of AR or MA terms. For seasonal models, spikes at multiples of the seasonal period (e.g., lag 12) suggest seasonal components.
Conditions
Requires basic time series output containing ACF and PACF plots.
Model Comparison using Information Criteria
Clear evidence
Shown in the video
Evidence
Audio
Observation
Speaker says 'under model comparison will show us overall summary statistics and fit statistics for these different models... we can see that our new model fits better according to the criteria such as AIC and SBC.'
Diagram
Observation
Model Comparison table showing AIC and SBC values for two different seasonal ARIMA models.
Method
Explanation
When multiple ARIMA models are fitted to the same time series, information criteria such as the Akaike Information Criterion (AIC) and the Schwarz Bayesian Criterion (SBC) are used to compare their goodness of fit while penalizing for model complexity. A lower AIC or SBC value indicates a better-fitting model.
Conditions
Requires fitting multiple candidate models to the same dataset.
Prerequisites
Seasonal ARIMA Model
Simultaneous fitting of ARIMA and seasonal ARIMA model groups
Clear evidence
Shown in the video
Evidence
Audio
Observation
“We can simultaneously fit a range of ARIMA and seasonal ARIMA models by selecting ARIMA Model Group under the red triangle.”
Animation
Observation
The cursor opens the red-triangle menu and selects “ARIMA Model Group,” then the “Specify ARIMA Model” dialog appears.
Method
Explanation
The clip demonstrates that JMP can fit multiple ARIMA and seasonal ARIMA candidates at once by choosing the ARIMA Model Group command from the red-triangle menu. The opened dialog lets the user specify ranges for the model terms rather than only a single fixed order.
Formula
Conditions
Use when comparing or estimating a group of ARIMA or seasonal ARIMA models.
Model orders and seasonal parameters are entered as ranges in the specification dialog.
Prerequisites
ARIMA
Seasonal ARIMA
p
d
q
P
D
Q
Periods Per Season = 12
Parameters available in the Specify ARIMA Model dialog
Clear evidence
Shown in the video
Evidence
Diagram
Observation
The “Specify ARIMA Model” dialog lists p, d, q under ARIMA and P, D, Q plus Periods Per Season under Seasonal ARIMA.
Diagram
Observation
The same dialog also shows Confidence Intervals 0.95, checked Intercept and Constrain fit boxes, Total Number of Models 0, and Cancel/Estimate buttons.
Uncertainties
The video does not explain the computational meaning of Constrain fit or why Total Number of Models is 0 in the shown state.
Definition
Explanation
The dialog exposes the standard ARIMA orders p, d, q and the seasonal ARIMA orders P, D, Q together with the seasonal period. It also provides a confidence-interval level and options for including an intercept and constraining the fit. These fields define the family of models to be estimated.
Formula
Conditions
Dialog is opened from the ARIMA Model Group command.
Seasonal ARIMA fields are present alongside ordinary ARIMA fields.
Prerequisites
p
d
q
P
D
Q
Periods Per Season = 12
Confidence Intervals = 0.95
Intercept
Constrain fit
Total Number of Models
Graph-based time-series diagnostics available from the report
Clear evidence
Shown in the video
Evidence
Audio
Observation
“Additional options are available under the topmost red triangle, including a variogram, spectral density, differencing, and lag plots.”
Animation
Observation
The cursor opens the top red-triangle Graph submenu and hovers over Variogram, Spectral Density, Difference, and Show Lag Plot.
Uncertainties
The clip names these diagnostics but does not define them mathematically.
Method
Explanation
From the top red-triangle Graph menu, the report offers several diagnostic views for time-series behavior: variogram, spectral density, differencing, and lag plot. These tools support inspection of dependence, periodicity, trend removal, and nonlinear relationships before or after model fitting.
Formula
Conditions
Available from the topmost red-triangle Graph menu of the time-series report.
Prerequisites
Lag / Autocorr / Partial
Ljung-Box Q
p-Value
Export and downstream use of a fitted ARIMA model
Clear evidence
Shown in the video
Evidence
Audio
Observation
“Under the red triangle for any of our model fits, we can also save our prediction formula, create a SAS job, or submit this ARIMA model to SAS using PROC ARIMA.”
Animation
Observation
The lower red-triangle menu shows Save Prediction Formula, Create SAS Job, and Submit to SAS; hovering Submit to SAS reveals the tooltip “Create a SAS job that opens a SAS window and runs the analysis in PROC ARIMA.”
Uncertainties
The actual prediction formula text is not shown in this clip.
Method
Explanation
For any fitted model in the report, the lower red-triangle menu allows the user to save the prediction formula, create a SAS job, or submit the ARIMA analysis to SAS through PROC ARIMA. This connects the interactive JMP fit to reproducible SAS code and external execution.
Formula
Conditions
Menu is accessed from the red triangle of a specific model fit report.
Prerequisites
ARIMA
Stationarity requirement for ARIMA modeling
Clear evidence
Shown in the video
Evidence
Audio
Observation
“ARIMA models require that the time series be stationary.”
Uncertainties
The video does not define stationarity formally (for example weak versus strict stationarity).
Definition
Explanation
The narration states a prerequisite for using ARIMA models: the time series being modeled must be stationary. In this clip, stationarity is presented as a condition that must be checked or enforced before fitting the model.
Formula
Conditions
Applies to ARIMA modeling as stated in the video.
The series must be stationary before fitting according to the narration.
Prerequisites
ARIMA
yt
Differencing as trend removal
Clear evidence
Shown in the video
Evidence
Audio
Observation
“If the series has a trend over time, differencing will remove the trend.”
Uncertainties
The video does not show the differencing operator formula or discuss seasonal differencing separately.
Method
Explanation
When a time series exhibits trend over time, the clip states that differencing can be used to remove that trend. This corresponds to the d parameter in the ARIMA specification and is presented as a way to achieve the stationarity required for ARIMA.
Formula
Conditions
Use when the series has a trend over time.
The goal is to make the series suitable for ARIMA by removing trend.
Prerequisites
d
Stationarity requirement for ARIMA modeling
yt
Log transformation for non-stationary variance
Clear evidence
Shown in the video
Evidence
Audio
Observation
“If the time series has a non-stationary variance, taking the log of the series may be helpful.”
Uncertainties
The video does not specify conditions under which the log transform fails, such as zero or negative observations.
Method
Explanation
If the variability of the time series changes over time, the narration recommends taking the logarithm of the series as a possible remedy. This is presented as a variance-stabilizing transformation rather than a trend-removal device.
Formula
Conditions
Use when the time series has non-stationary variance.
The transformation is suggested as potentially helpful, not guaranteed.
Prerequisites
Stationarity requirement for ARIMA modeling
yt
Transfer functions for forecasting with input variables
Clear evidence
Shown in the video
Evidence
Audio
Observation
“To forecast the time series with input variables, we can use transfer functions under the red triangle, as long as we specified those input variables when we first set up the model.”
Animation
Observation
The cursor opens the red-triangle menu and hovers over Transfer Function.
Uncertainties
The video does not define the transfer-function model mathematically or show its equation.
Method
Explanation
The clip states that if one wants to forecast using input variables, the Transfer Function option under the red triangle can be used. A key condition is that those input variables must already have been specified when the model was initially set up.
Formula
Conditions
Input variables must have been specified during initial model setup.
Used for forecasting the time series with exogenous inputs.
Prerequisites
ARIMA
Where to find more information on ARIMA in JMP
Clear evidence
Shown in the video
Evidence
Audio
Observation
“For more information on time series and ARIMA models, search for ARIMA in the JMP Help or in the book Specialized Models.”
Method
Explanation
The closing narration directs users to two reference sources for further detail on time series and ARIMA models: JMP Help and the book titled Specialized Models.
Formula
Conditions
Intended as follow-up reading after viewing the demonstration.
Prerequisites
ARIMA
Claims and conditions · 4
ARIMA requires stationarity
Clear evidence
Shown in the video
Evidence
Audio
Observation
“ARIMA models require that the time series be stationary.”
Uncertainties
The claim is stated without a formal definition of stationarity or proof.
Proposition
Statement
ARIMA models require that the time series be stationary.
Hypotheses
The model class under discussion is ARIMA.
The data are a time series.
Quantifiers
Universal as stated in the narration for ARIMA models.
Differencing removes trend
Clear evidence
Shown in the video
Evidence
Audio
Observation
“If the series has a trend over time, differencing will remove the trend.”
Uncertainties
The statement is absolute in wording, but the clip gives no proof or qualification about trend type or residual trend after differencing.
Proposition
Statement
If the series has a trend over time, differencing will remove the trend.
Hypotheses
The time series has a trend over time.
Quantifiers
Conditional universal statement as spoken.
Log transform may help non-stationary variance
Clear evidence
Shown in the video
Evidence
Audio
Observation
“If the time series has a non-stationary variance, taking the log of the series may be helpful.”
Uncertainties
The narration uses “may be helpful,” so this is a suggestive claim rather than a guarantee.
Proposition
Statement
If the time series has a non-stationary variance, taking the log of the series may be helpful.
Hypotheses
The time series has non-stationary variance.
Quantifiers
Existential/pragmatic suggestion rather than a theorem.
Transfer functions require pre-specified input variables
Clear evidence
Shown in the video
Evidence
Audio
Observation
“...we can use transfer functions under the red triangle, as long as we specified those input variables when we first set up the model.”
Uncertainties
The clip does not show the setup step where input variables are specified.
Proposition
Statement
Transfer functions can be used to forecast the time series with input variables only if those input variables were specified when the model was first set up.
Hypotheses
Forecasting is to be done with input variables.
The model was initially set up with those input variables specified.
Quantifiers
Conditional requirement stated for use of transfer functions.
Derivations and proofs · 1
Preprocessing sequence implied for ARIMA readiness
Clear evidence
Shown in the video
Evidence
Audio
Observation
The narrator first states the stationarity requirement, then gives differencing for trend and log transformation for non-stationary variance.
Uncertainties
This is a procedural explanation, not a formal derivation or proof.
Intuitive argument
Steps
Expression
Explanation
Start from the requirement that ARIMA models need a stationary time series.
Justification
Directly stated in the narration at 34–38 seconds.
Shown in the video
Expression
Explanation
If the observed series has trend over time, apply differencing to remove the trend.
Justification
Directly stated in the narration at 38–42 seconds.
Shown in the video
Expression
Explanation
If the series instead has non-stationary variance, consider taking the logarithm of the series.
Justification
Directly stated in the narration at 42–48 seconds.
Shown in the video
Conclusion
The clip presents a simple diagnostic-to-remedy workflow: check stationarity, use differencing for trend, and use a log transform for changing variance.
Worked examples · 2
Forecasting Steel Shipments with Seasonal ARIMA
Clear evidence
Shown in the video
Evidence
Audio
Observation
Speaker introduces the 'steel shipments data set' and walks through the entire modeling process.
Diagram
Observation
JMP software interface showing the data table, dialogs, and output reports for the steel shipments time series.
Problem
Explore and forecast a single time series (steel shipments) using ARIMA models in JMP.
Given
Monthly steel shipments data from 01/01/1984 to 12/01/1991.
Data is sorted by time and evenly spaced.
Goal
Identify an appropriate seasonal ARIMA model and compare its fit against alternative specifications.
Steps
Expression
Analyze→Modeling→Time Series
Explanation
Open the Time Series platform in JMP.
Justification
Standard procedure in JMP for time series analysis.
Shown in the video
Expression
Y,TimeSeries=Steel Shipments,X,TimeID=Date
Explanation
Assign the shipment values to the Y role and the dates to the X (Time ID) role.
Justification
Defines the dependent variable and the time index for the analysis.
Shown in the video
Expression
Observe ACF and PACF plots
Explanation
Examine the basic diagnostics to suggest initial model orders.
Justification
ACF and PACF plots reveal autocorrelation structures indicative of AR and MA terms.
Shown in the video
Expression
ARIMA(2,0,0)(1,0,0)12
Explanation
Fit the first seasonal ARIMA model based on the initial diagnosis (non-seasonal AR=2, seasonal AR=1).
Justification
Captures the primary autocorrelation patterns observed in the data.
Shown in the video
Expression
Expand Residuals section
Explanation
Check the residual diagnostics (ACF, PACF, Ljung-Box) of the first model.
Justification
Residual analysis determines if the model has adequately captured the data's structure or if further refinement is needed.
Shown in the video
Expression
ARIMA(2,0,3)(1,0,0)12
Explanation
Fit a second model by adding a non-seasonal moving average component of order 3.
Justification
Attempts to improve the fit by accounting for additional short-term correlation structures in the residuals.
Shown in the video
Expression
Compare AIC and SBC
Explanation
Use the Model Comparison report to evaluate the two fitted models.
Justification
Information criteria provide a quantitative basis for selecting the best model among candidates.
Shown in the video
Answer
The second model, Seasonal ARIMA(2, 0, 3)(1, 0, 0)12, fits better than the first model, Seasonal ARIMA(2, 0, 0)(1, 0, 0)12, as indicated by its lower AIC (1401.9792 vs 1410.7669) and SBC (1419.9297 vs 1421.0233).
Verification
The conclusion is verified by directly comparing the numerical values in the Model Comparison table shown in the software output.
Steel Shipments seasonal ARIMA report example
Clear evidence
Shown in the video
Evidence
Diagram
Observation
The report title reads “Time Series Steel Shipments” and the selected model is “Seasonal ARIMA(2, 0, 0)(1, 0, 0)12”.
Diagram
Observation
The Model Comparison table lists two seasonal ARIMA fits with DF, Variance, AIC, SBC, RSquare, -LogLikH, and Weights values.
Diagram
Observation
The Model Summary table shows DF 92, Sum of Squared Errors 11470010, Variance Estimate 124674.022, Standard Deviation 353.092087, Akaike's 'A' Information Criterion 1410.76594, Stable Yes, Invertible Yes.
Uncertainties
The clip does not walk through how the displayed fitted coefficients were obtained.
Problem
Inspect an existing time-series ARIMA report for Steel Shipments and identify the fitted seasonal model and available follow-up commands.
Two compared models are visible in the Model Comparison table.
Diagnostics table shows lags 21–25 with Autocorr, Ljung-Box Q, p-Value, and Partial values.
Goal
Identify the displayed model form and the software actions available for model-group specification, diagnostics, export, and transfer-function forecasting.
Steps
Expression
Explanation
Read the selected model label from the report header.
Justification
Visible on screen throughout the clip.
Shown in the video
Expression
Explanation
Note that the model is seasonal ARIMA with ordinary orders (2,0,0), seasonal orders (1,0,0), and seasonal period 12.
Justification
Directly encoded in the displayed title Seasonal ARIMA(2, 0, 0)(1, 0, 0)12.
Shown in the video
Expression
Explanation
Open the red-triangle ARIMA Model Group command to see the specification dialog for p, d, q, P, D, Q, and Periods Per Season.
Justification
Shown by cursor action at 3–12 seconds.
Shown in the video
Expression
Explanation
Use the top red-triangle Graph menu to access variogram, spectral density, difference, and lag plot diagnostics.
Justification
Shown and named at 13–22 seconds.
Shown in the video
Expression
Explanation
Use the lower red-triangle menu to save the prediction formula, create a SAS job, or submit to SAS via PROC ARIMA.
Justification
Shown and narrated at 23–33 seconds.
Shown in the video
Expression
Explanation
Use Transfer Function only when input variables were specified during initial model setup.
Justification
Narrated at 48–58 seconds while the menu item is highlighted.
Shown in the video
Answer
The example report displays a fitted Seasonal ARIMA(2, 0, 0)(1, 0, 0)12 model for Steel Shipments and demonstrates the surrounding workflow for model-group estimation, diagnostics, export, and transfer-function forecasting.
Verification
The answer matches the persistent on-screen report title, the visible model comparison and summary tables, and the menu items demonstrated in the clip.
Visual events · 7
Displaying the Steel Shipments Dataset
Clear evidence
Shown in the video
Evidence
Diagram
Observation
A JMP data table titled 'Steel Shipments.jmp' is displayed, showing columns for 'Date' and 'Steel Shipments' with monthly data.
Objects
Data table
Date column
Steel Shipments column
Changes
None, static display of the dataset.
Invariants
The structure of the time series data (monthly observations).
Interpretation
Establishes the raw data being analyzed, highlighting the time index and the target variable.
Generating Basic Time Series Diagnostics
Clear evidence
Shown in the video
Evidence
Diagram
Observation
The 'Time Series Basic Diagnostics' report appears, featuring a scatterplot of the series, an ACF plot, and a PACF plot.
Objects
Scatterplot of Steel Shipments over time
ACF plot
PACF plot
Ljung-Box Q statistics
Changes
The software calculates and displays the autocorrelation and partial autocorrelation structures of the raw time series.
Invariants
The underlying data remains unchanged.
Interpretation
Provides visual and statistical evidence of the time series' dependencies, which guides the initial selection of ARIMA model orders.
Comparing Fitted ARIMA Models
Clear evidence
Shown in the video
Evidence
Diagram
Observation
The 'Model Comparison' table is expanded, showing rows for two different seasonal ARIMA models and columns for fit statistics like DF, Variance, AIC, and SBC.
Objects
Model Comparison table
AIC column
SBC column
Changes
Two different model specifications are evaluated side-by-side using information criteria.
Invariants
The dataset used for fitting both models is the same.
Interpretation
Allows for a direct, quantitative comparison of model performance, facilitating the selection of the optimal ARIMA specification based on parsimony and fit.
Opening the ARIMA Model Group dialog
Clear evidence
Shown in the video
Evidence
Animation
Observation
The cursor opens the red-triangle menu, moves through ARIMA-related items, selects ARIMA Model Group, and the Specify ARIMA Model dialog appears.
Objects
Red-triangle dropdown menu
ARIMA Model Group menu item
Specify ARIMA Model dialog
p, d, q fields
P, D, Q fields
Periods Per Season field
Confidence Intervals field
Intercept checkbox
Constrain fit checkbox
Total Number of Models field
Cancel and Estimate buttons
Changes
Menu expands.
ARIMA Model Group is selected.
Dialog window opens in the center of the report.
Cursor hovers over the dialog fields and then over Cancel.
Invariants
The underlying Steel Shipments time-series report remains visible behind the dialog.
The selected model title remains Seasonal ARIMA(2, 0, 0)(1, 0, 0)12.
Interpretation
This visual sequence demonstrates that model-group estimation is configured through a dedicated dialog exposing both nonseasonal and seasonal ARIMA orders.
Browsing graph-based diagnostic options
Clear evidence
Shown in the video
Evidence
Animation
Observation
The cursor opens the top red-triangle Graph submenu and highlights Variogram, Spectral Density, Difference, and Show Lag Plot.
Objects
Top red-triangle menu
Graph submenu
Variogram
Spectral Density
Difference
Show Lag Plot
Cross Correlation
Prewhitening
Changes
Submenu expands.
Different diagnostic items are highlighted in sequence.
Invariants
The main report tables and plots remain unchanged in the background.
Interpretation
The clip visually inventories the diagnostic graphics available for exploring time-series structure beyond the basic ARIMA fit.
Exporting or submitting the fitted ARIMA model
Clear evidence
Shown in the video
Evidence
Animation
Observation
The cursor opens the lower red-triangle menu for the selected model and highlights Save Prediction Formula, Create SAS Job, and Submit to SAS.
Diagram
Observation
A tooltip appears for Submit to SAS stating that it creates a SAS job that opens a SAS window and runs the analysis in PROC ARIMA.
Objects
Lower red-triangle menu
Save Prediction Formula
Create SAS Job
Submit to SAS
Residual Statistics submenu
Tooltip text
Changes
Menu opens.
Cursor moves down the list.
Tooltip appears when Submit to SAS is hovered.
Invariants
The selected model remains the same seasonal ARIMA fit shown in the report.
Interpretation
This sequence shows how a fitted model can be reused outside the current report, especially through saved formulas or SAS PROC ARIMA submission.
Highlighting Transfer Function for exogenous forecasting
Clear evidence
Shown in the video
Evidence
Animation
Observation
The cursor reopens the red-triangle menu and hovers over Transfer Function while the narration discusses forecasting with input variables.
Objects
Red-triangle menu
Transfer Function menu item
Changes
Menu reopens.
Transfer Function is highlighted.
Invariants
No new dialog opens during this interval.
The report content behind the menu stays the same.
Interpretation
The visual emphasis pairs the menu location with the spoken condition that transfer functions are available only if input variables were specified earlier.
Misconceptions · 2
Fitting ARIMA directly to a nonstationary series
Clear evidence
Shown in the video
Evidence
Audio
Observation
The narrator explicitly says ARIMA models require stationarity and then describes remedies for trend and non-stationary variance.
Misconception
One might think ARIMA can be applied directly to any time series regardless of trend or changing variance.
Clarification
The clip states that ARIMA requires a stationary series; trend should be addressed by differencing and non-stationary variance may be addressed by taking logs.
Using transfer functions without prior input-variable setup
Clear evidence
Shown in the video
Evidence
Audio
Observation
“...as long as we specified those input variables when we first set up the model.”
Misconception
One might assume transfer functions can be added afterward even if no input variables were defined initially.
Clarification
The narration states that transfer functions can be used only if the input variables were specified when the model was first set up.
Concept relations · 8
Diagnosing ARIMA Orders via ACF and PACF → Seasonal ARIMA Model
Clear evidence
Shown in the video
Evidence
Audio
Observation
Speaker explicitly links the ACF/PACF plots to the suggested ARIMA orders.
Application
Explanation
The method of diagnosing ARIMA orders using ACF and PACF plots is directly applied to determine the parameters for the seasonal ARIMA model.
Seasonal ARIMA Model → Model Comparison using Information Criteria
Clear evidence
Shown in the video
Evidence
Audio
Observation
Speaker discusses comparing the newly fitted models using the Model Comparison report.
Application
Explanation
The seasonal ARIMA models generated are the subjects being evaluated by the model comparison method.
Stationarity requirement for ARIMA modeling → Simultaneous fitting of ARIMA and seasonal ARIMA model groups
Clear evidence
Shown in the video
Evidence
Audio
Observation
The stationarity statement immediately follows the ARIMA demonstration and frames the modeling requirements.
Prerequisite
Explanation
The clip presents stationarity as a requirement that must hold before ARIMA model fitting is appropriate.
Differencing as trend removal → Stationarity requirement for ARIMA modeling
Clear evidence
Shown in the video
Evidence
Audio
Observation
Differencing is introduced right after the stationarity requirement as the remedy for trend.
Application
Explanation
Differencing is described as a method for removing trend so that the series can satisfy the stationarity condition needed for ARIMA.
Log transformation for non-stationary variance → Stationarity requirement for ARIMA modeling
Clear evidence
Shown in the video
Evidence
Audio
Observation
The log transformation is introduced as a response to non-stationary variance after the stationarity requirement.
Application
Explanation
Taking logs is presented as a variance-stabilizing step that helps make the series more suitable for ARIMA modeling.
Parameters available in the Specify ARIMA Model dialog → Simultaneous fitting of ARIMA and seasonal ARIMA model groups
Clear evidence
Shown in the video
Evidence
Audio
Observation
The narration refers to fitting “ARIMA and seasonal ARIMA models” together.
Diagram
Observation
The dialog separates ARIMA and Seasonal ARIMA parameters but places them in one specification window.
Uncertainties
The video does not explicitly say “seasonal ARIMA generalizes ARIMA,” but the interface clearly nests seasonal terms within the broader ARIMA model-group workflow.
Contains
Explanation
The model-group workflow contains both ordinary ARIMA parameters and seasonal ARIMA parameters in one specification process.
Transfer functions for forecasting with input variables → Simultaneous fitting of ARIMA and seasonal ARIMA model groups
Clear evidence
Shown in the video
Evidence
Audio
Observation
Transfer functions are introduced as a way to forecast the time series with input variables.
Uncertainties
The clip does not provide the transfer-function equation.
Generalizes
Explanation
Transfer functions extend the univariate ARIMA setting by allowing forecasting with specified input variables.
Export and downstream use of a fitted ARIMA model → Simultaneous fitting of ARIMA and seasonal ARIMA model groups
Clear evidence
Shown in the video
Evidence
Audio
Observation
The narrator says the fitted ARIMA model can be saved as a prediction formula or submitted to SAS using PROC ARIMA.
Application
Explanation
The export and submission features operate on the ARIMA model that was fitted through the model-group workflow.
Find an answer · 10
How do you specify the non-seasonal and seasonal orders (p, d, q, P, D, Q) for an ARIMA model in JMP?
Clear evidence
Shown in the video
Evidence
Diagram
Observation
The Seasonal ARIMA Specification dialog is shown.
Knowledge points
Seasonal ARIMA Model
Why are ACF and PACF plots used before fitting an ARIMA model?
Clear evidence
Shown in the video
Evidence
Audio
Observation
Speaker explains how the plots suggest the model components.
Knowledge points
Diagnosing ARIMA Orders via ACF and PACF
What criteria should be used to select the best ARIMA model among several candidates?
Clear evidence
Shown in the video
Evidence
Diagram
Observation
Model Comparison table with AIC and SBC values.
Knowledge points
Model Comparison using Information Criteria
How do I fit a range of ARIMA and seasonal ARIMA models at once in JMP?
Clear evidence
Shown in the video
Evidence
Audio
Observation
Narration explains simultaneous fitting of a range of ARIMA and seasonal ARIMA models via ARIMA Model Group.
Knowledge points
Simultaneous fitting of ARIMA and seasonal ARIMA model groups
Parameters available in the Specify ARIMA Model dialog
What do p, d, q, P, D, Q, and Periods Per Season mean in the ARIMA model dialog?
Clear evidence
Shown in the video
Evidence
Diagram
Observation
The Specify ARIMA Model dialog shows p, d, q, P, D, Q, Periods Per Season, Confidence Intervals, Intercept, and Constrain fit.
Knowledge points
Parameters available in the Specify ARIMA Model dialog
p
d
q
P
D
Q
Periods Per Season = 12
Where are variogram, spectral density, differencing, and lag plot options located in the time-series report?
Clear evidence
Shown in the video
Evidence
Audio
Observation
The narrator lists variogram, spectral density, differencing, and lag plots under the top red triangle.
Knowledge points
Graph-based time-series diagnostics available from the report
How can I save the prediction formula or send a fitted ARIMA model to SAS PROC ARIMA?
Clear evidence
Shown in the video
Evidence
Audio
Observation
The narrator says one can save the prediction formula, create a SAS job, or submit the model to SAS using PROC ARIMA.
Knowledge points
Export and downstream use of a fitted ARIMA model
Why must the time series be stationary before fitting ARIMA, and what do I do if it has trend or changing variance?
Clear evidence
Shown in the video
Evidence
Audio
Observation
The narration states ARIMA requires stationarity and then gives differencing and log-transform remedies.
Knowledge points
Stationarity requirement for ARIMA modeling
Differencing as trend removal
Log transformation for non-stationary variance
When can I use transfer functions for forecasting with input variables?
Clear evidence
Shown in the video
Evidence
Audio
Observation
The narrator says transfer functions can be used as long as input variables were specified when the model was first set up.
Knowledge points
Transfer functions for forecasting with input variables
Where does the video say to look for more information on ARIMA and time series in JMP?
Clear evidence
Shown in the video
Evidence
Audio
Observation
The closing line points to JMP Help and the book Specialized Models for more information.
Knowledge points
Where to find more information on ARIMA in JMP
Coverage and review notes
Covered · Introductory logo animation, no mathematical content.
Covered · Introduction to the dataset and setting up the Time Series platform in JMP.
Covered · Generation and interpretation of basic time series diagnostics (ACF/PACF).
Covered · Specification and estimation of the first seasonal ARIMA model.
Covered · Expanding the residuals section to check model adequacy.
Covered · Specification and estimation of a second, more complex seasonal ARIMA model.
Covered · Comparing the two fitted models using AIC and SBC information criteria.
Covered · Opening report view, narration about fitting ARIMA and seasonal ARIMA model groups, and the Specify ARIMA Model dialog.
Covered · Top red-triangle Graph menu showing variogram, spectral density, difference, and lag plot options.
Covered · Lower red-triangle menu for saving prediction formula, creating SAS job, and submitting to SAS PROC ARIMA.
Covered · Spoken prerequisites for ARIMA: stationarity, differencing for trend, and log transformation for non-stationary variance.
Covered · Transfer Function menu item and the condition that input variables must have been specified during initial setup.
Covered · Closing reference to JMP Help and the book Specialized Models, followed by brief silence/end of clip.
Reviewed English material v1: card/concept_card "Setting Up Time Series Analysis in JMP" starting at 0:20 — To analyze a time series in JMP, navigate to Analyze > Modeling > Time Series. Assign your target variable to the 'Y, Time Series' role and your temporal index to the 'X, Time ID' role. Ensure your data is sorted chronologically and evenly spaced; if the Time ID is omitted, the software assumes equal spacing between observations.
Reviewed English material v1: card/concept_card "Specifying a Seasonal ARIMA Model" starting at 0:54 — A Seasonal ARIMA model is denoted as ARIMA(p,d,q)(P,D,Q)s. The lowercase parameters (p, d, q) control the non-seasonal autoregressive order, differencing order, and moving average order, respectively. The uppercase parameters (P, D, Q) control the corresponding seasonal components. The parameter 's' represents the number of periods in a full seasonal cycle (e.g., s=12 for monthly data). ARIMA(p,d,q)(P,D,Q)s
Reviewed English material v1: card/concept_card "Evaluating Model Adequacy via Residuals" starting at 1:08 — After fitting an ARIMA model, it is crucial to examine the residual diagnostics. Expanding the 'Residuals' section in the output reveals the ACF, PACF, and Ljung-Box statistics of the residuals. If the residuals resemble white noise (i.e., no significant autocorrelation), the model has adequately captured the underlying structure of the time series. Otherwise, a different model specification may be required.